
U.S. data center construction costs rose 13% in 2026, more than twice the global rate, as AI demand ran ahead of powered land, power connections and skilled labour.
The latest annual data centre construction cost index puts a number on what many of us already feel in project budgets: building for AI got noticeably more expensive this year.
What it means for MEP designers
Most of that premium sits in our scope: liquid cooling loops, denser electrical distribution and compressed schedules that leave little room for redesign. When contractors price in acceleration and overtime allowances, late MEP changes get expensive fast, so coordinated models and early equipment decisions matter more than ever. The labour squeeze is also why MEP contractors with data center backlogs are being bought up, as in the EMCOR and P1 Construction deal, and why manufacturers are adding capacity, like the new Airedale data centre chiller line in Texas.
Are you seeing liquid cooling and power constraints change how early MEP gets involved on data center projects?
Russian version: https://bim3d.org/threads/stoimost-...sla-na-13-v-2026-godu-vdvoe-bystree-mira.505/
The latest annual data centre construction cost index puts a number on what many of us already feel in project budgets: building for AI got noticeably more expensive this year.
US Data Center Construction Costs Rise 13% in 2026
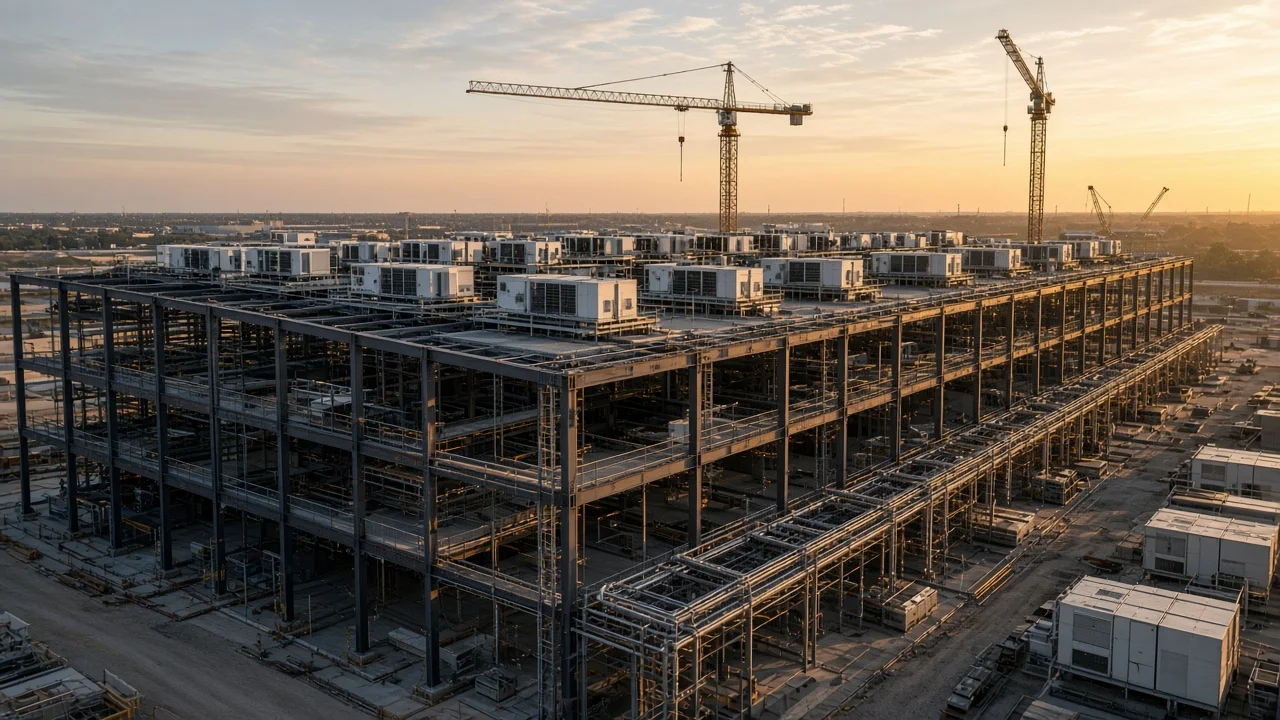
Hyperscale data center under construction with rooftop cooling plant and pipe racks. U.S. data...
- Average cost per watt in North America and Europe is up 13% year on year, more than double the global rate and roughly three times the ten-year average.
- The index covers 62 markets, over 500 live or recent projects and a survey of more than 400 industry leaders.
- In the U.S., AI-ready facilities cost around 10% more than traditional ones, driven by higher rack density, liquid cooling and faster delivery schedules.
- For a typical 60 MW design, Silicon Valley comes in at $15.01 per watt and Dallas at $10.51.
- 56% of respondents call power a major obstacle; about half wait one to two years for a utility connection, almost a third more than two.
- Only about a quarter in North America say contractor capacity is sufficient. Cost growth is expected to ease to 6–10% next year.
What it means for MEP designers
Most of that premium sits in our scope: liquid cooling loops, denser electrical distribution and compressed schedules that leave little room for redesign. When contractors price in acceleration and overtime allowances, late MEP changes get expensive fast, so coordinated models and early equipment decisions matter more than ever. The labour squeeze is also why MEP contractors with data center backlogs are being bought up, as in the EMCOR and P1 Construction deal, and why manufacturers are adding capacity, like the new Airedale data centre chiller line in Texas.
Are you seeing liquid cooling and power constraints change how early MEP gets involved on data center projects?
Russian version: https://bim3d.org/threads/stoimost-...sla-na-13-v-2026-godu-vdvoe-bystree-mira.505/